Why Choosing the Right Wealth Management Firm Matters
You’ve worked hard to build your wealth. Now you want a trusted partner who can help you protect and grow what you’ve accumulated, coordinate your financial picture, and plan for the transitions ahead — whether that’s retirement, selling a business, or passing wealth to the next generation. Choosing the right wealth management firm may be one of the most consequential financial decisions you can make.
Research in behavioral economics consistently shows that one of the greatest risks to long-term financial outcomes is investor behavior such as selling in a downturn, chasing performance, or making emotional decisions during major life events. A comprehensive wealth management solution can help you avoid those costly mistakes, and more.
Yet not all wealth management firms are created equal. Some operate as fiduciaries, like Mercer Advisors, legally bound to act in your best interests. Others operate under a suitability standard, meaning they must recommend products that are suitable for you but not necessarily the best option available. Some offer integrated, comprehensive planning. Others focus narrowly on investment management. Understanding these differences — and knowing what questions to ask — can help you make an informed, confident decision.
This guide walks you through a 12-criterion selection framework outlining key questions to ask any prospective firm and ways to evaluate whether a firm is positioned to serve your full financial picture.
When you know how to choose a wealth management firm, you can make a decision with confidence.
The 12-Criterion Selection Framework
When evaluating a wealth management firm, these 12 criteria can help you assess whether a firm is equipped to serve your needs.
1. Fiduciary status
A fiduciary is legally obligated to act in your best interests at all times, not just when a transaction takes place. Registered investment advisers (RIAs) are held to fiduciary principles under the Investment Advisers Act of 1940, which imposes a duty of care and a duty of loyalty on advisors.1 The duty of care requires an advisor to provide advice that is in the best interests of the client. The duty of loyalty requires the advisor to eliminate or make full and fair disclosure of all conflicts of interest.
Ask any prospective firm directly: “Are you a fiduciary for all solutions, not just some?” If the firm is dually registered — meaning it operates as both an RIA and a broker-dealer — make sure you’re clear on exactly when each standard applies.
Mercer Advisors was established as an independent RIA in 1985.
2. Integrated tax, estate, and investment planning
Wealth management is distinct from asset management, which focuses on investment portfolios. A wealth management firm may offer comprehensive planning that can include tax planning, estate planning, investment management, insurance planning, and more. This integrated approach means your advisor understands how a decision in one area affects the others — for example, how a Roth conversion affects your tax picture and your estate plan at the same time.
A 2026 survey found that 68% of advised clients would consider switching to another financial advisor that offers estate planning solutions.2 That statistic underscores how much clients value having all their financial needs met by one unified team. This is one more reason why understanding how to choose a wealth management firm matters.
3. Fee transparency
Find out the fee structure of any firm you’re considering. Most wealth managers charge a fee based on a percentage of assets under management (AUM). Research shows that 92% of advisors incorporate AUM fees in some form, while 86% of advisory firms rely on AUM fees as their primary method of charging for advice.3 The median rate is about 1% on portfolios up to $1 million and drops as assets grow, falling to around 0.50% for portfolios above $5 million.4
Ask the firm: “What is your total annual fee, and what solutions are included? Do you receive any commissions from product sales? What are the average expense ratios for recommended funds?” A firm that is transparent about all costs — not just the management fee — demonstrates a commitment to putting your interests first.
4. Credentials
Look for professional credentials that signal rigorous training and ethical standards. The Certified Financial Planner® (CFP®) professional certification requires completing college-level coursework in personal financial planning, passing a comprehensive exam, accumulating 6,000 hours of professional experience, and adhering to a code of ethics.5 The Chartered Financial Analyst® (CFA®) designation signals investment management expertise. A certified public accountant (CPA) brings tax expertise.
Ask: “What credentials do your advisors hold? How do those credentials inform the advice you provide?”
5. Custody
Most RIAs don’t hold your assets directly. They manage your investments through an account held at a qualified custodian — typically a large, independent financial institution. This separation provides an important safeguard: The firm managing your money is not the firm holding your money.
Ask: “Who is your custodian? How are my assets held, and how can I confirm their protection?”
6. Technology
A firm’s technology platform affects everything from portfolio reporting to financial planning tools to secure document sharing. Modern wealth management firms use technology to give you real-time access to your accounts, performance reports, and planning documents.
Ask: “What technology do you use to help me track my progress? Can I access my accounts online? How do you protect my data?”
7. Communication
Clear, consistent communication is the backbone of a strong advisor relationship. Some firms meet quarterly; others meet annually. Some offer video meetings; others prefer in-person. The right cadence depends on your preferences and the complexity of your situation.
Ask: “How often do we meet? What happens between meetings? Who do I contact if I have a question?”
8. Team approach
A single advisor, no matter how talented, can’t be a specialist in everything. Look for a firm, like Mercer Advisors, that provides a team of professionals who work together on your behalf. This team approach means you can benefit from specialized knowledge across disciplines without having to coordinate multiple professionals yourself.
Ask: “Do I work with one person or a team? Who handles tax questions? Who handles estate planning questions?”
9. Solution model
Understand what solutions are included in your agreement and what costs extra. Some firms offer comprehensive financial planning, tax preparation, estate plan coordination, and investment management bundled into one fee. Others charge separately for each solution.
Ask: “What’s included in my fee? What solutions cost extra?”
10. Succession planning
Ask what happens if your advisor retires, leaves, or becomes incapacitated. A firm with a succession plan and a deep bench of talent helps ensure continuity. A firm’s longevity can offer insight into its experience navigating changing markets, client needs, and industry conditions.
Ask: “What’s your succession plan? If my advisor leaves, who takes over my account?”
11. Complaint history
Every registered financial or wealth advisor has a publicly available record. You can use FINRA’s BrokerCheck tool or the Securities and Exchange Commission’s Investment Adviser Public Disclosure (IAPD) database to research any professional’s employment history, qualifications, and disclosure events.6
Ask: “Has the firm had any regulatory actions or complaints against it or its advisors?” Then verify the answer yourself using BrokerCheck.
12. Cultural fit
Finally, consider whether the firm’s culture and philosophy align with your values.
- Do they listen to your goals, or do they lead with products?
- Do they explain things in plain language, or do they rely on jargon?
The advisor-client relationship is a long-term partnership, and trust is its foundation.
Integrated Strategies: How Planning, Tax, Estate, and Investments Work Together
Choosing a firm that offers integrated planning means your financial life can be coordinated, not fragmented. Here are four strategies that illustrate how integrated planning works in practice. As you’re researching how to choose a wealth management firm, these strategies can help you evaluate what integration looks like.
Strategy 1: Coordinating tax planning with investment management
Tax-efficient investing is about more than picking the right investments. It’s about where you hold them, when you harvest losses, and how you manage gains. A firm that coordinates tax planning with investment management can help you use tax-loss harvesting to offset capital gains, position assets strategically across taxable and tax-advantaged accounts, and time portfolio rebalancing to lessen tax drag. This coordinated approach may help improve after-tax outcomes over time.
Strategy 2: Aligning estate planning with investment decisions
Your investment decisions and your estate plan should inform each other. For example, if your estate plan calls for leaving assets to charity, your investment strategy should account for that future distribution. A firm that aligns estate planning with investment management can help ensure your portfolio reflects your legacy goals — not just your return targets.
Strategy 3: Using insurance to protect accumulated wealth
Insurance planning is often overlooked in wealth management, yet it plays a critical role in protecting what you’ve built. A firm that includes insurance planning alongside investment and estate planning can help you evaluate whether your coverage matches your wealth level, your dependents’ needs, and your long-term care plans. Integrated insurance planning helps your protection strategy evolve as your life circumstances change.
Strategy 4: Comprehensive financial planning as the foundation
Comprehensive financial planning ties everything together. A financial plan accounts for your income, expenses, assets, liabilities, tax situation, estate plan, insurance coverage, and retirement goals. It serves as the foundation for every investment decision, every tax move, and every estate planning step. A firm that builds this foundation first — before recommending investments — demonstrates a planning-first philosophy that keeps your goals at the center.
Questions To Ask Before You Hire a Wealth Management Firm
Here is a selection of key questions drawn from the 12-criterion framework above. Use these in your initial interview with any prospective firm or advisor. These questions can help you understand how to choose a wealth management firm that fits your needs:
Evaluation Checklist
Red Flags To Watch For When Evaluating a Firm
As you evaluate firms, watch for these warning signs:
- Pressure to move quickly. A reputable firm gives you time to decide. High-pressure sales tactics can suggest the firm’s interests come before yours.
- Vague fee answers. A firm should be able to clearly explain what you pay — including all costs, not just the management fee.
- No written planning process. A firm that can’t show you a sample financial plan or describe its planning methodology may not have a structured approach.
- No team depth. If one person handles everything, you may be vulnerable if that person leaves or retires.
- Unclear custody arrangements. If a firm holds your assets directly rather than using a qualified, independent custodian, that may be a concern.
Taking the Next Step
Choosing a wealth management firm is not a decision to rush. Take the time to interview multiple firms, ask the questions in this guide, and compare their answers. A complimentary consultation can help you assess fit before you commit. Knowing how to choose a wealth management firm can help you make this important decision with greater confidence.
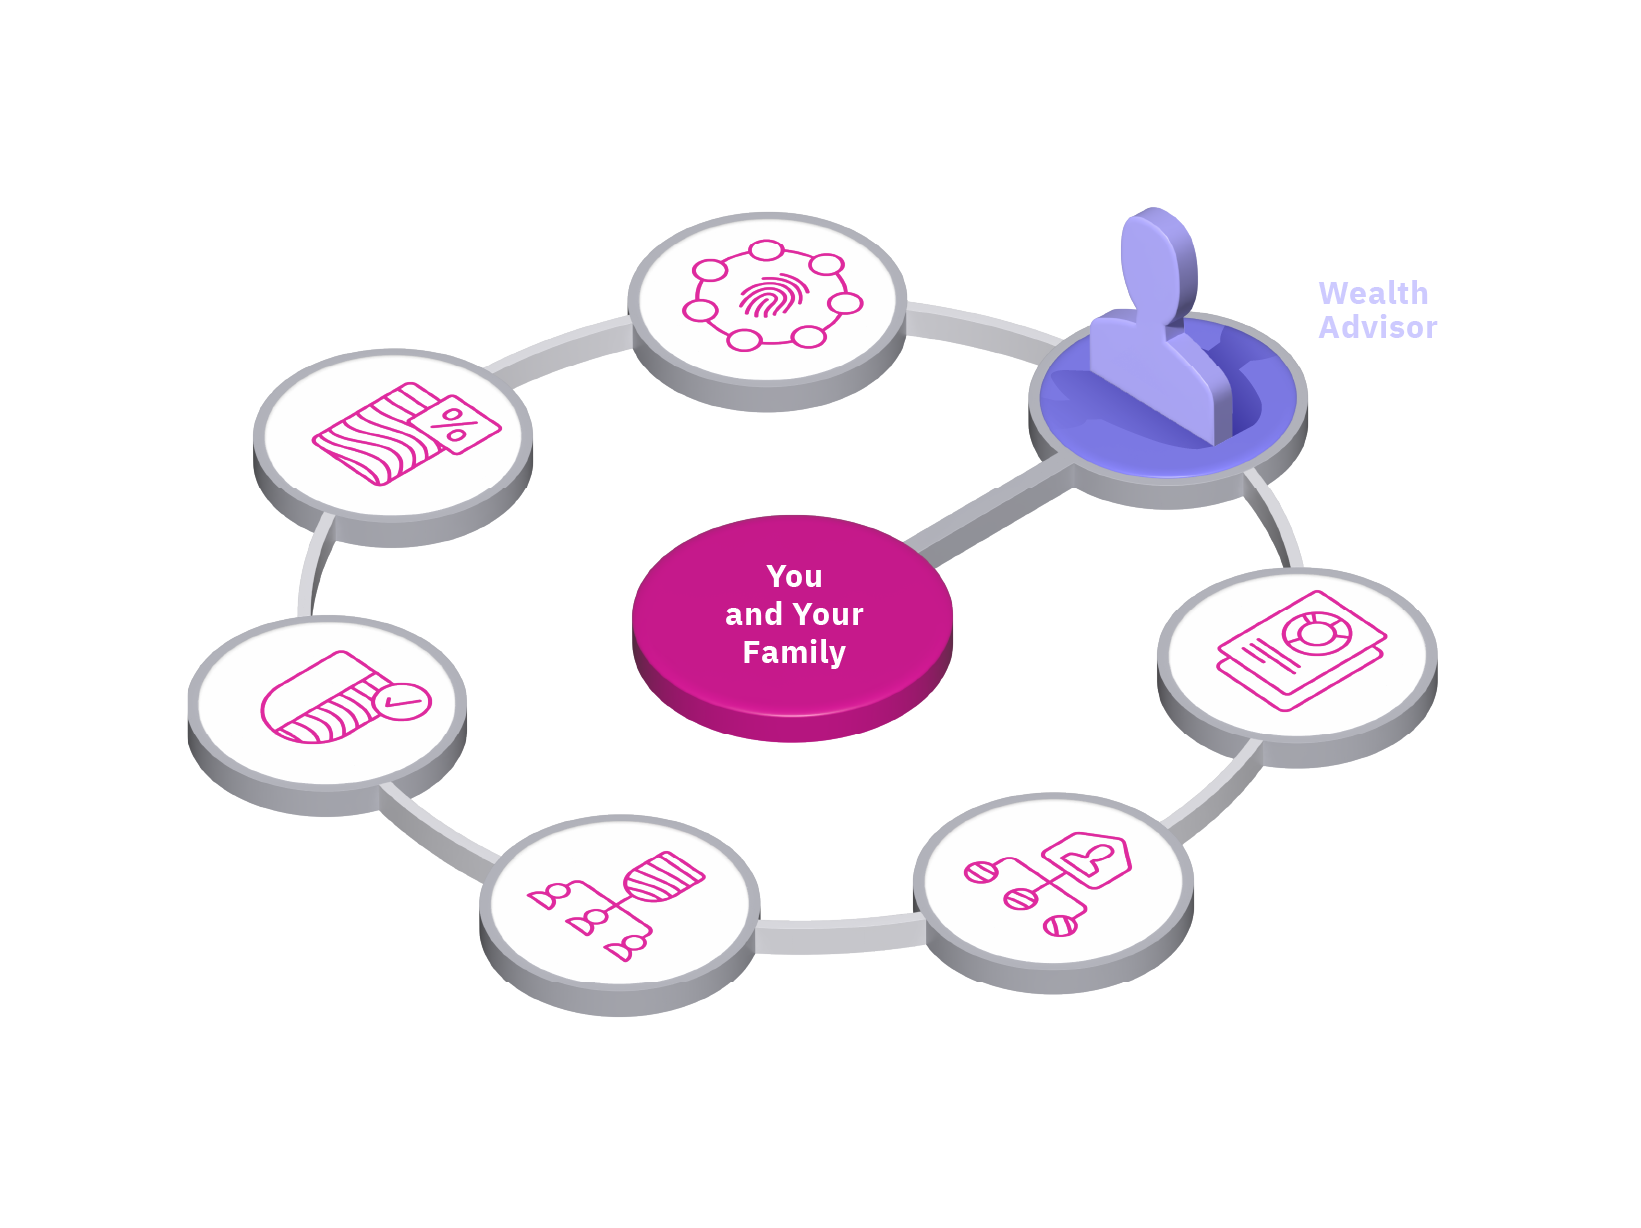
At Mercer Advisors, we’ve spent more than 40 years making the comprehensive, time-tested approach that many ultra-high-net-worth individuals use to manage their financial lives, which is accessible to more families. A dedicated wealth advisor coordinates specialists from our financial planning, tax planning and preparation, estate planning, insurance solutions, investment management teams and other specialties to help ensure every aspect of your financial life is attended to.
Our wealth advisors are compensated through a fee-based model with no sales goals. We’ve intentionally separated sales and solution roles so the people responsible for your ongoing plan are not the people incentivized to bring in new accounts.
Many Mercer Advisors’ wealth advisors and associates are CERTIFIED FINANCIAL PLANNER® professionals, and some hold additional designations. You can view a directory and read profiles of our client-facing employees on our website: Meet our advisory team.
Our clients tend to stay for the long term — on average 10 years — because the relationship is built on trust, not transactions.
If you’re ready to see what integrated wealth management looks like, and learn more about our firm, contact us for a complimentary consultation.
FAQs
-
A wealth management firm is a firm that may provide comprehensive financial solutions that go beyond investment management to include tax planning, estate planning, financial planning, and insurance planning. Unlike an asset manager who focuses on your investment portfolio, a wealth management firm may coordinate all aspects of your financial life so every decision works together. This integrated approach helps ensure your investments, taxes, estate plan, and insurance coverage align with your goals.
-
Fiduciaries are legally required to act in your best interests at all times. Brokers, by contrast, operate under a suitability standard, meaning they must recommend products that are suitable for you but not necessarily the best option available. Registered investment advisers (RIAs) are held to the fiduciary standard under the Investment Advisers Act of 1940, which imposes a duty of care and a duty of loyalty on the advisor.
-
Managing your own investments can work if you have the time, knowledge, and discipline to stay on top of your portfolio, taxes, and estate plan. Many people find that as their wealth grows, the complexity of coordinating all these areas becomes challenging. A wealth management firm may bring a team of specialists who work together on your behalf, so you can focus on your life rather than your paperwork.
-
Having a CPA and an estate attorney is a strong foundation, but a wealth management firm can add value by coordinating all your advisors so your tax strategy, estate plan, and investment decisions work together. Without a coordinator, you may need to manage communication among your advisors yourself, which can lead to gaps or conflicting recommendations. An integrated firm can serve as the central point of contact for your full financial picture.
-
Use FINRA’s BrokerCheck, a free tool that lets you research the professional backgrounds of wealth advisors and firms. BrokerCheck shows employment history, qualifications, and any regulatory actions or complaints. You can also search the Securities and Exchange Commission’s Investment Adviser Public Disclosure database for information about registered independent adviser firms and their representatives.
-
Most wealth managers charge a percentage of assets under management, with the median rate at about 1% on portfolios up to $1 million, declining as assets grow. Independent registered investment advisers (RIAs) typically offer fee-based or fee-only structures without commissions, while wire houses and broker-dealers may charge additional fees or earn commissions on products. The key is to ask for total costs — including management fees, expense ratios, and transaction fees — so you can compare firms on an all-in basis.
1“2026 Examination Priorities.” U.S. Securities and Exchange Commission, Nov. 17, 2025.
2“Trust & Will 2026 Financial Advisor Report.” Trust & Will, July 6, 2026.
3“Trends in Financial Advice Fees: What Financial Advisors Are Actually Charging for Their Services.” Kitces, June 16, 2025.
4“Trends in Financial Advice Fees: What Financial Advisors Are Actually Charging for Their Services.” Kitces, June 16, 2025.
5“Competency Standards for CFP® Certification.” CFP Board, 2026.
6“BrokerCheck.” FINRA, 2026.
All expressions of opinion reflect the judgment of the author as of the date of publication and are subject to change. Some of the research and ratings shown in this presentation come from third parties that are not affiliated with Mercer Advisors. The information is believed to be accurate but is not guaranteed or warranted by Mercer Advisors. Content, research, tools and stock or option symbols are for educational and illustrative purposes only and do not imply a recommendation or solicitation to buy or sell a particular security or to engage in any particular investment strategy.
For financial planning advice specific to your circumstances, talk to a qualified professional at Mercer Advisors
Mercer Advisors is not a law firm and does not provide legal advice to clients. All Estate planning document preparation and other legal advice are provided through select third parties, with which Mercer Advisors has a contractual relationship. Tax preparation and filing services are provided by Mercer Advisors Tax Services, LLC. Clients will sign a separate agreement when engaging Mercer Advisors Tax Services that defines the services provided and any additional fees that may apply. Insurance products are provided by Mercer Advisors Insurance Services, LLC (MAIS), which places individual life, disability, long term care coverage, and property and casualty coverage through select insurance companies. Trustee services are offered through select third parties with which a client would sign an additional agreement, and additional fees may apply.